Prairie Lily Financial
  • Link to LinkedIn
  • Link to X
  • Services
    • Individuals & Families
      • Single Parents
      • Females and Finances
      • Financial Advice
      • Insurance Planning
      • Retirement Planning
      • Estate Planning for Young Families
      • Estate Planning for Retirees and Mature Families
      • Estate Planning for Blended Families
    • Business Owners
      • Financial Advice
      • Insurance Planning
      • Estate Planning for Business Owners
      • Group Health Benefits
      • Pensions and Retirement Benefits
    • Health Professionals
      • Financial Advice
      • Retirement Planning
    • Insurance
      • Disability Insurance
      • Critical Illness Insurance
      • Mortgage Insurance
      • Life Insurance
      • Personal Life Insurance
      • Corporate Life Insurance
      • Travel Insurance
    • Investments
      • Registered Education Savings Plans (RESPs)
      • Tax-Free Savings Account (TFSA)
      • Registered Retirement Savings Plan
      • Registered Retirement Income Fund
      • Annuities
      • Advantage Account
  • About
    • About
    • Suppliers
    • Resources
    • Privacy and Website Terms of Use
  • Blog
  • Contact
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu

Archive for category: Coronavirus – Associates

Federal Budget 2021 Highlights

April 22, 2021/in 2021, Blog, Coronavirus, Coronavirus - Associates, Coronavirus - Practice Owners, Coronavirus - Students, corporate, Debt, Family, financial advice, Financial Planning, incorporated professionals, individuals, personal finances, Professional Corporations, tax/by Financial Tech Tools

On April 19, 2021, the Federal Government released their 2021 budget. We have broken down the highlights of the financial measures in this budget into three different sections:

  • Business Owners

  • Personal Tax Changes

  • Supplementary Highlights

Business Owners

Extending Covid -19 Emergency Business Supports

All of the following COVID-19 Emergency Business Supports will be extended from June 5, 2021, to September 25, 2021, with the subsidy rates gradually decreasing:

  • Canada Emergency Wage Subsidy (CEWS) – The maximum wage subsidy is currently 75%. It will decrease down to 60% for July, 40% for August, and 20% for September.

  • Canada Emergency Rent Subsidy (CERS) – The maximum rent subsidy is currently 65%. It will decrease down to 60% for July, 40% for August, and 20% for September.

  • Lockdown Support Program – The Lockdown Support Program rate of 25% will be extended from June 4, 2021, to September 25, 2021.

Only organizations with a decline in revenues of more than 10% will be eligible for these programs as of July 4, 2021. The budget also includes legislation to give the federal government authority to extend these programs to November 20, 2021, should either the economy or the public health situation make it necessary.

Canada Recovery Hiring Program

The federal budget introduced a new program called the Canada Recovery Hiring Program. The goal of this program is to help qualifying employers offset costs taken on as they reopen. An eligible employer can claim either the CEWS or the new subsidy, but not both.

The proposed subsidy will be available from June 6, 2021, to November 20, 2021, with a subsidy of 50% available from June to August. The Canada Recovery Hiring Program subsidy will decrease down to 40% for September, 30% for October, and 20% for November.

Interest Deductibility Limits

The federal budget for 2021 introduces new interest deductibility limits. This rule limits the amount of net interest expense that a corporation can deduct when determining its taxable income. The amount will be limited to a fixed ratio of its earnings before interest, taxes, depreciation, and amortization (sometimes referred to as EBITDA).

The fixed ratio will apply to both existing and new borrowings and will be phased in at 40% as of January 1, 2023, and 30% for January 1, 2024.

Support for small and medium-size business innovation

The federal budget also includes 4 billion dollars to help small and medium-sized businesses innovate by digitizing and taking advantage of e-commerce opportunities. Also, the budget provides additional funding for venture capital start-ups via the Venture Capital Catalyst Program and research that will support up to 2,500 innovative small and medium-sized firms.

Personal Tax Changes

Tax treatment and Repayment of Covid-19 Benefit Amounts

The federal budget includes information on both the tax treatment and repayment of the following COVID-19 benefits:

  • Canada Emergency Response Benefits or Employment Insurance Emergency Response Benefits

  • Canada Emergency Student Benefits

  • Canada Recovery Benefits, Canada Recovery Sickness Benefits, and Canada Recovery Caregiving Benefits

Individuals who must repay a COVID-19 benefit amount can claim a deduction for that repayment in the year they received the benefit (by requesting an adjustment to their tax return), not the year they repaid it. Anyone considered a non-resident for income tax purposes will have their COVID-19 benefits included in their taxable income.

Disability Tax Credit

Eligibility changes have been made to the Disability Tax Credit. The criteria have been modified to increase the list of mental functions considered necessary for everyday life, expand the list of what can be considered when calculating time spent on therapy, and reduce the requirement that therapy is administered at least three times each week to two times a week (with the 14 hours per week requirement remaining the same).

Old Age Security

The budget enhances Old Age Security (OAS) benefits for recipients who will be 75 or older as of June 2022. A one-time, lump-sum payment of $500 will be sent out to qualifying pensioners in August 2021, with a 10% increase to ongoing OAS payments starting on July 1, 2022.

Waiving Canada Student Loan Interest

The budget also notes that the government plans to introduce legislation that will extend waiving of any interest accrued on either Canada Student Loans or Canada Apprentice Loans until March 31, 2023.

Support for Workforce Transition

Support to help Canadians transition to growing industries was also included in the budget. The support is as follows:

  • $250 million over three years to Innovation, Science and Economic Development Canada to help workers upskill and redeploy to growing industries.

  • $298 million over three years for the Skills for Success Program to provide training in skills for the knowledge economy.

  • $960 million over three years for the Sectoral Workforce Solutions Program to help design and deliver training relevant to the needs of small and medium businesses.

Supplementary Highlights

Federal Minimum Wage

The federal budget also introduces a proposed federal minimum wage of $15 per hour that would rise with inflation.

New Housing Rebate

The GST New Housing Rebate conditions will be changed. Previously, if two or more individuals were buying a house together, all of them must be acquiring the home as their primary residence (or that of a relation) to qualify for the GST New Housing Rebate. Now, the GST New Housing Rebate will be available as long as one of the purchasers (or a relation of theirs) acquires the home as their primary place of residence. This will apply to all agreements of purchase and sale entered into after April 19, 2021.

Unproductive use of Canadian Housing by Foreign Non-Resident Owners

A new tax was introduced in the budget on unproductive use of Canadian housing by non-resident foreign owners. This tax will be a 1% tax on the value of non-resident, non-Canadian owned residential real estate considered vacant or underused. This tax will be levied annually starting in 2022.

All residential property owners in Canada (other than Canadian citizens or permanent residents of Canada) must also file an annual declaration for the prior calendar year with the CRA for each Canadian residential property they own, starting in 2023. Filing the annual declaration may qualify owners to claim an exemption from the tax on their property if they can prove the property is leased to qualified tenants for a minimum period in a calendar year.

Excise Duty on Vaping and Tobacco

The budget also includes a new proposal on excise duties on vaping products and tobacco. The proposed framework would consist of:

  • A single flat rate duty on every 10 millilitres of vaping liquid as of 2022

  • An increase in tobacco excise duties by $4 per carton of 200 cigarettes and increases to the excise duty rates for other tobacco products such as tobacco sticks and cigars as of April 20, 2021.

Luxury Goods Tax

Finally, the federal budget proposed introducing a tax on certain luxury goods for personal use as of January 1, 2022.

  • For luxury cars and personal aircraft, the new tax is equal to the lesser of 10% of the vehicle’s total value or the aircraft, or 20% of the value above $100,000.

  • For boats over $250,000, the new tax is equal to the lesser of 10% of the full value of the boat or 20% of the value above $250,000.

If you have any questions or concerns about how the new federal budget may impact you, call us – we’d be happy to help you!
https://prairielilyfinancial.com/wp-content/uploads/2021/04/FEDERAL-BUDGET-2021.jpg 281 500 Financial Tech Tools https://prairielilyfinancial.com/wp-content/uploads/2020/09/prairieLilyFinancail.png Financial Tech Tools2021-04-22 10:37:312021-04-22 12:03:35Federal Budget 2021 Highlights

Extended COVID-19 Federal Emergency Benefits

February 22, 2021/in Blog, Coronavirus, Coronavirus - Associates, Coronavirus - Practice Owners, Coronavirus - Retiring/by Financial Tech Tools

On Friday, February 19, 2021, Prime Minister Justin Trudeau announced an extension to several of the COVD-19 federal emergency benefits.  The goal of this extension is to support Canadians who are still being financially impacted by the COVID-19 pandemic.

The following benefits are impacted:

  • Canada Recovery Benefit 

  • Canada Recovery Caregiving Benefit

  • Canada Recovery Sickness Benefit 

  • Employment Insurance

Canada Recovery Benefit

The Canada Recovery Benefit (CRB) provides income support to anyone who is:

  • Employed or self-employed, but not entitled to Employment Insurance (EI) benefits.

  • Has had their income reduced by at least 50 percent due to COVID-19. 

You can receive up to $1,000 ($900 after taxes withheld) a week every two weeks for the CRB. The recent changes now allow you to apply for this benefit for a total of 38 weeks – previously the maximum was 26 weeks.  

Canada Recovery Caregiving Benefit

The Canada Recovery Caregiving Benefit (CRCB) helps support people who cannot work because they must supervise a child under 12 or other family members due to COVID-19. For example, a school is closed due to COVID-19 or your child must self-isolate because they have COVID-19.  

You can receive $500 ($450 after taxes withheld) for each 1-week period you claim the CRCB. The recent extension made now allows you to apply for this benefit for a total of 38 weeks instead of the previous 26 weeks. 

Canada Recovery Sickness Benefit

The $500 a week ($450 after taxes) Canada Recovery Sickness Benefit (CRSB) is also getting a boost. If you cannot work because you are sick or need to self-isolate due to COVID-19, you can now apply for this benefit for a total of four weeks. Previously, this benefit would only cover up to two missed weeks of work. 

Employment Insurance 

Finally, the government will also be increasing the amount of time you can claim Employment Insurance (EI) benefits. You will now be able to claim EI for a maximum of 50 weeks – this is an increase of 24 weeks from the previous eligibility maximum.

For full details, go to https://www.canada.ca/en/revenue-agency/campaigns/covid-19-update/covid-19-benefits-credits-support-payments.html

https://prairielilyfinancial.com/wp-content/uploads/2021/02/COVID-19-Benefits-extended.png 281 500 Financial Tech Tools https://prairielilyfinancial.com/wp-content/uploads/2020/09/prairieLilyFinancail.png Financial Tech Tools2021-02-22 14:09:462021-02-22 16:06:20Extended COVID-19 Federal Emergency Benefits

Self-employed: Government of Canada addresses CERB repayments for some ineligible self-employed recipients

February 12, 2021/in Blog, Coronavirus, Coronavirus - Associates, Coronavirus - Practice Owners/by Financial Tech Tools

Great news for some ineligible self-employed Canadians who received the Canada Emergency Response Benefit (CERB). As per canada.ca:

“Today, the Government of Canada announced that self-employed individuals who applied for the Canada Emergency Response Benefit (CERB) and would have qualified based on their gross income will not be required to repay the benefit, provided they also met all other eligibility requirements. The same approach will apply whether the individual applied through the Canada Revenue Agency or Service Canada.

This means that, self-employed individuals whose net self-employment income was less than $5,000 and who applied for the CERB will not be required to repay the CERB, as long as their gross self-employment income was at least $5,000 and they met all other eligibility criteria.

Some self-employed individuals whose net self-employment income was less than $5,000 may have already voluntarily repaid the CERB. The CRA and Service Canada will return any repaid amounts to these individuals. Additional details will be available in the coming weeks.”

For full details, see full news release at https://www.canada.ca/en/revenue-agency/news/2021/02/government-of-canada-announces-targeted-interest-relief-on-2020-income-tax-debt-for-low–and-middle-income-canadians.html

https://prairielilyfinancial.com/wp-content/uploads/2021/02/Self-employed.png 281 500 Financial Tech Tools https://prairielilyfinancial.com/wp-content/uploads/2020/09/prairieLilyFinancail.png Financial Tech Tools2021-02-12 16:28:222021-02-12 18:03:26Self-employed: Government of Canada addresses CERB repayments for some ineligible self-employed recipients

Personal Tax Planning Tips – End of 2020 Tax Year

December 2, 2020/in 2020 Only, Blog, Charitable Gifting, Coronavirus, Coronavirus - Associates, Coronavirus - Practice Owners, Coronavirus - Retired, Coronavirus - Retiring, Coronavirus - Students, disability, disability insurance, Family, financial advice, Financial Planning, health benefits, pension plan, rdsp, Registered Education Savings Plan, rrsp, tax, Tax Free Savings Account/by Financial Tech Tools

Now that we are reaching the end of the tax year, it’s an excellent time to review your finances. We’ve listed below some of the critical areas to consider and provide you with useful guidelines.

We have divided our tax planning tips into five sections:

  • Tax Deadlines

  • Individual tax issues

  • Family tax issues

  • Managing your investments

  • Retirement planning

Tax Deadlines for 2020 Savings

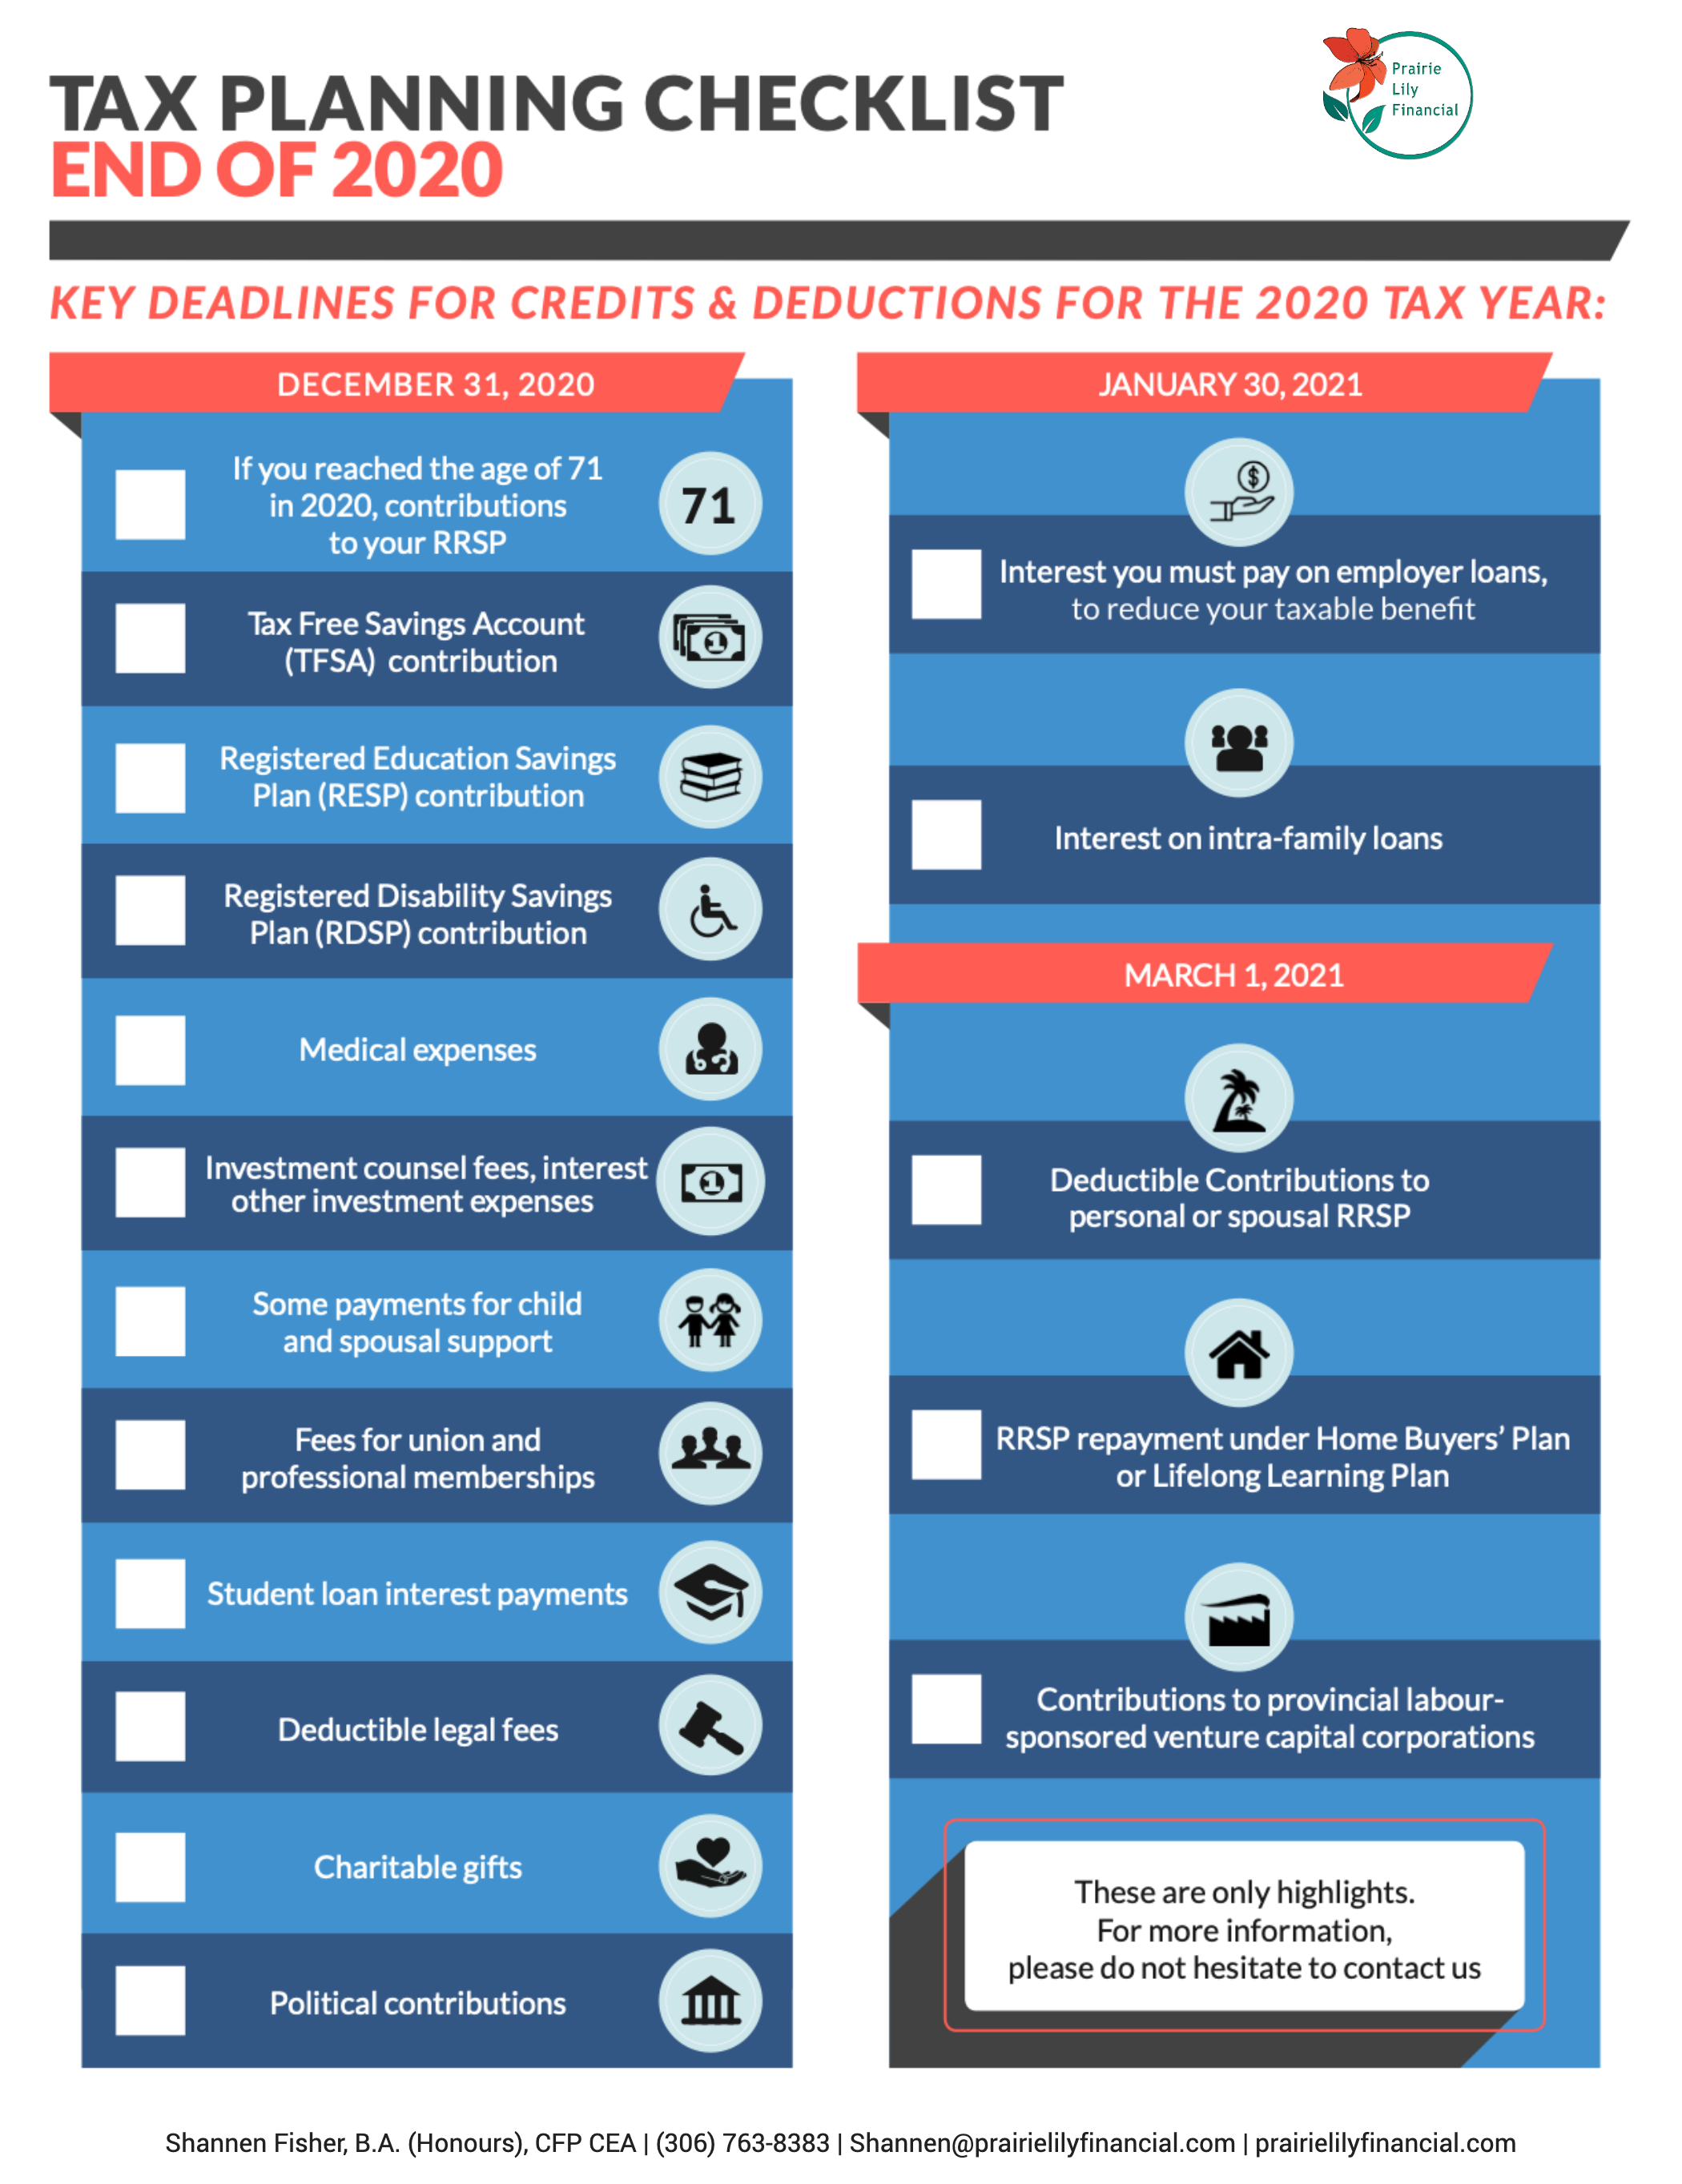
December 31, 2020:

  • If you reached the age of 71 in 2020, you can’t contribute to your RRSP after this date

  • Use up your TFSA contribution room

  • Contribute to an RESP to get the Canadian Education Savings Grant (CESG) and the income-tested Canada Learning Bond (if eligible).

  • Contribute to an RDSP to get the Canada Disability Savings Grant (CDSG) and the income-tested Canada Disability Savings Bond (if eligible).

  • Medical expenses

  • Investment counsel fees, interest and other expenses relating to investments

  • Some payments for child and spousal support

  • Fees for union and professional memberships

  • Student loan interest payments

  • Deductible legal fees

  • Charitable gifts

  • Political contributions

January 30, 2021

  • Interest on intra-family loans

  • The interest you must pay on employer loans to reduce your taxable benefit

March 1, 2021

  • Contributions to provincial labour-sponsored venture capital corporations

  • RRSP Repayment under Home Buyers Plan or Lifelong Learning Plan

  • Deductible contributions to a personal or spousal RRSP

Individual Tax Issues

To help Canadians deal with financial hardships due to job loss because of COVID-19, the Canadian government introduced several benefit programs. If you received any of these benefits, you should be aware of the tax ramifications.

The Canada Emergency Response Benefit (CERB) was the first benefit program issued by the government and ran until September 26, 2020. If you received the CERB at all during 2020, the government will issue you at T4A, showing how much money you received from the CERB program. You must then declare that as income when filing your 2020 income tax return. Since no tax was taken off at the source, be sure to put aside money to pay for potential income taxes on your CERB income.

As of September 27, 2020, the government offered three replacement benefit programs:

  • Canada Recovery Benefit (CRB)
    This is for people impacted by COVID-19 who work but are not eligible for EI (e.g. self-employed).

  • Canada Recovery Sickness Benefit (CRSB)
    This is for people who are employed cannot work due to COVID-19 and do not have access to paid sick leave.

  • Canada Recovery Caregiving Benefit (CRCB)
    This is for people who must miss work to care for a family member who has COVID-19.

For all three of these programs, the government will be withholding 10% in taxes upfront, but you may end up owing extra tax, depending on the rest of your income for 2020, so it’s important to set extra money aside for taxes.

Also, there is a unique condition for the CRB only. If you make over $38,000 in 2020 (excluding the CRB), you will have to pay back the CRB at a rate of 50 cents for each dollar of CRB you earned above the threshold.

If you paid interest on an eligible student loan in 2020, you can claim a non-refundable tax credit in the amount of interest you paid by December 31. In addition, you should be aware that student loan payments were frozen for six months – from March 30 to September 30. No interest accrued on student loans during that period.

Family Tax Issues

  • Check your eligibility for the Canada Child Benefit
    (CCB)
    To receive the Canada Child Benefit in 2021/22, you need to file your tax returns for 2020 as the benefit is calculated using your family income from the previous year. Eligibility for the CCB depends on set criteria such as your family’s income, how many children you have, and how old they are. You may qualify for a full or partial amount, depending on whether you have full custody or shared custody.

  • Consider family income splitting

    The CRA offers a prescribed low-interest rate on family loans. Therefore, it makes sense to consider setting up an income splitting loan arrangement with your family members. If you do this, you can potentially lock in a family loan at a low-interest rate of 1% and then invest the borrowed money into a higher return investment while benefitting from your family member’s lower tax status. Don’t forget to adhere to the Tax on Split Income rules.

Managing Your Investments

  • Use up your TFSA contribution room

    If you can, it’s worth contributing the full $6,000 to your TFSA for 2020. You can also contribute more (up to $69,500) if you are 29 or older and haven’t made any previous TFSA contributions.

  • Contribute to a Registered Education Savings Plan (RESP)

    The Registered Education Savings Plan (RESP) is a savings plan for parents and others to save for a child’s education. The Canada Education Savings Grant (CESG) will match up to 20% of your contributions up to a maximum of $2,500.

    That means the CESG can add a maximum of $500 to an RESP each year. The grant room accumulates until your child turns 17. Therefore, any unused CESG amounts for the current year are automatically carried forward for possible use in the future years.

    The income-tested Canada Learning Bond (CLB) is paid directly to a child’s RESP by the Canadian government to low-income families. No personal contributions are required to receive the CLB.

  • Contribute to a Registered Disability Savings Plan (RDSP)

    The Registered Disability Savings Plan (RDSP) is a savings plan for parents and others to save for the financial security of a person who is eligible for the Disability Tax Credit (DTC). The government will pay a matching Canada Disability Savings Grant (CDSG) up to 300% – depending on the beneficiary’s adjusted family net income and amount contributed.

    Also, low-income Canadians with disabilities may be eligible for a Canada Disability Savings Bond (CDSB). If you qualify, it will be paid directly to your RDSP.

    The government will pay matching grants or bonds into the RSDP up to and including the end of the year the recipient turns 49. Be aware that there is a 10-year carry-forward of CDSG and CDSB entitlements.

  • Donate securities to charity

    Donating by year-end will provide you with tax savings. If you donate eligible securities or mutual funds, capital gains tax does not apply, and you can receive a tax receipt for their full market value. Also, the charity gets the full value of the securities.

  • Think about selling any investments with unrealized capital losses

    It might be worth doing this before year-end to apply the loss against any net capital gains achieved during the last three years. The last trading date for 2020 for Canadian and US publicly traded stocks will be Tuesday December 29th in order to record the gain or loss in the 2020 taxation year.

    Conversely, if you have investments with unrealized capital gains that cannot be offset with capital losses, it may be worth selling them after 2020 to be taxed on the income the following year.

  • Consider the timing of purchasing of certain non-registered investments

    Suppose you are considering purchasing an interest-bearing investment like a guaranteed investment certificate (GIC) with a maturity date of one year or more. In that case, you may consider delaying the purchase to the following year, so you don’t have to pay tax on accrued interest until 2021. You should also consider this with mutual funds that make taxable distributions before the end of 2020, consider delaying this until early 2021. Don’t pay taxes earlier than necessary.

  • Check if you have investments in a corporation

    The new passive investment income rules apply to tax years from 2018 onwards. They state that the small business deduction is reduced for companies with between $50,000 and $150,000 of investment income. Therefore, the small business deduction has entirely stopped for corporations that earn a passive investment income of more than $150,000.

    Note – At a provincial level, both Ontario and New Brunswick do not follow the federal rules to limit access to the small business deduction.

Retirement Planning

  • Make the most of your RRSP

    The deadline for making contributions to your RRSP for the year 2020 is March 1, 2021. The deduction limit for 2020 is limited to 18% of the income you earned in 2020, to a maximum of $27,230. This maximum amount is impacted by the following:

  1. Any pension adjustment

  2. Any previous unused RRSP contribution room

  3. Any pension adjustment reversal.

Remember that deducting your RRSP contribution reduces your after-tax cost of making said contribution.

  • Check when your RRSP is due to end

    If you reach the age of 71 during 2020, you must wind up your RRSP this year. You must make your final contribution to it by December 31, 2020.

  • Convert to RRIF before year-end

    If you turned 65 during 2020 or are already older than 65, you’re entitled to a pension credit that can fully or partly offset the tax on the first $2,000 of eligible income annually. Consider setting up an RRIF before year-end to pay out $2,000 annually if you don’t have any other eligible pension income.

If you have any questions about your taxes for 2020, contact us – we can help you!

https://prairielilyfinancial.com/wp-content/uploads/2020/12/[email protected] 563 1000 Financial Tech Tools https://prairielilyfinancial.com/wp-content/uploads/2020/09/prairieLilyFinancail.png Financial Tech Tools2020-12-02 14:07:542020-12-02 15:03:56Personal Tax Planning Tips – End of 2020 Tax Year

Book a Meeting

Get in Touch

, 

T: 
E:

,

  • Why A Buy-Sell Agreement Is Vital For Your Business
  • Tax Tips You Need To Know Before Filing Your 2022 Taxes
  • When and Why You Should Conduct an Insurance Audit
  • Federal Budget 2023 Highlights
  • Saskatchewan 2023 Budget Highlights

About

Cultivating financial security and independence for you and your loved ones. Our goal for our clients is to grow financial prosperity for anyone who wants it through financial education.

pride
©2020 Financial Tech Tools Inc. | Privacy Statement and Terms of Use
  • Link to LinkedIn
  • Link to X
Scroll to top Scroll to top Scroll to top