Prairie Lily Financial
  • Link to LinkedIn
  • Link to X
  • Services
    • Individuals & Families
      • Single Parents
      • Females and Finances
      • Financial Advice
      • Insurance Planning
      • Retirement Planning
      • Estate Planning for Young Families
      • Estate Planning for Retirees and Mature Families
      • Estate Planning for Blended Families
    • Business Owners
      • Financial Advice
      • Insurance Planning
      • Estate Planning for Business Owners
      • Group Health Benefits
      • Pensions and Retirement Benefits
    • Health Professionals
      • Financial Advice
      • Retirement Planning
    • Insurance
      • Disability Insurance
      • Critical Illness Insurance
      • Mortgage Insurance
      • Life Insurance
      • Personal Life Insurance
      • Corporate Life Insurance
      • Travel Insurance
    • Investments
      • Registered Education Savings Plans (RESPs)
      • Tax-Free Savings Account (TFSA)
      • Registered Retirement Savings Plan
      • Registered Retirement Income Fund
      • Annuities
      • Advantage Account
  • About
    • About
    • Suppliers
    • Resources
    • Privacy and Website Terms of Use
  • Blog
  • Contact
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu

Archive for category: health benefits

Retirement Planning for Business Owners – Checklist
October 4, 2022/in Blog, Business Owners, corporate, health benefits, life insurance, long term care, pension plan, rrsp, Tax Free Savings Account/by Financial Tech Tools

As a business owner, one of your challenges is learning how to balance between reinvesting into the business and setting money aside for personal savings. Since there are no longer employer-sponsored pension plans and the knowledge that retirement will come eventually, it’s important to have a retirement plan in place.

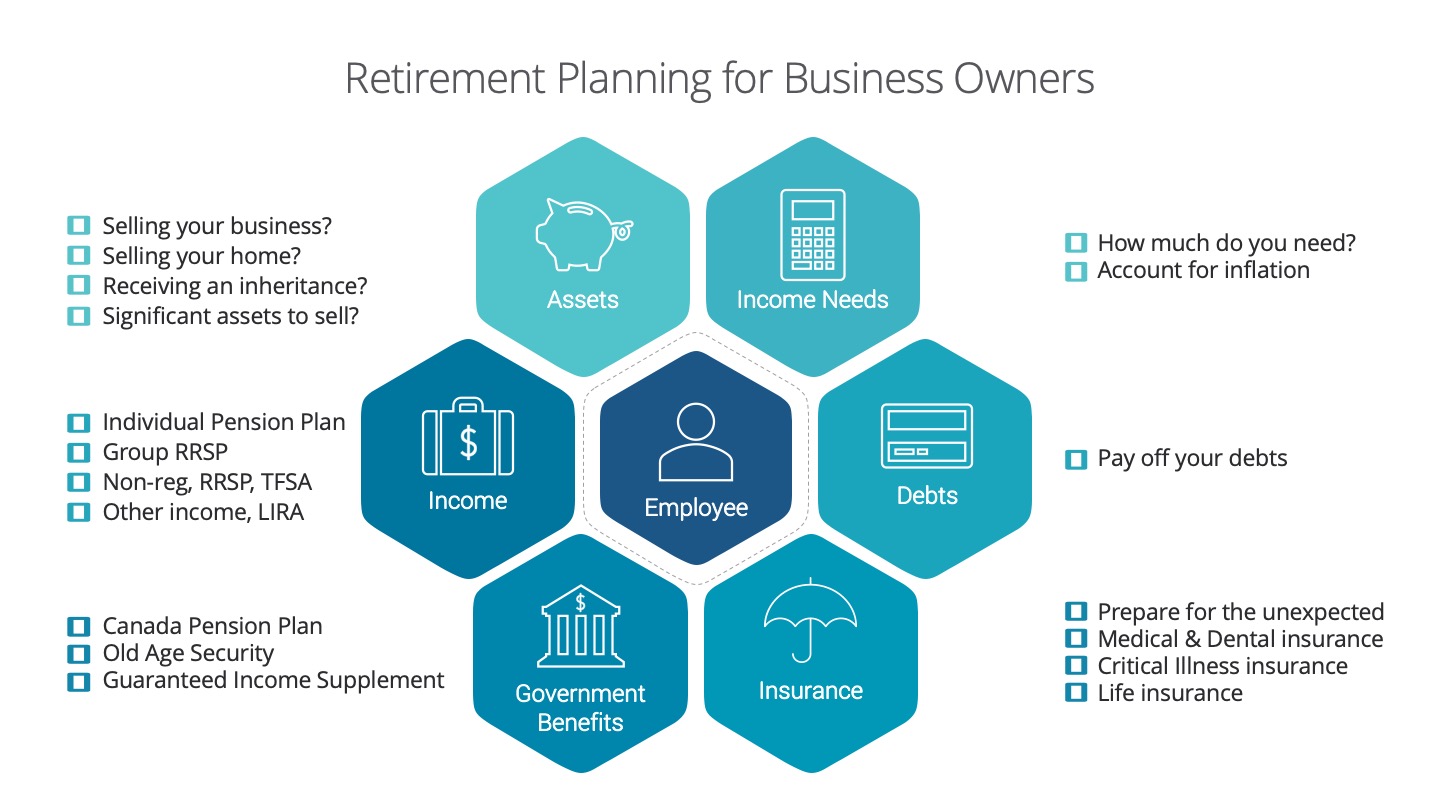
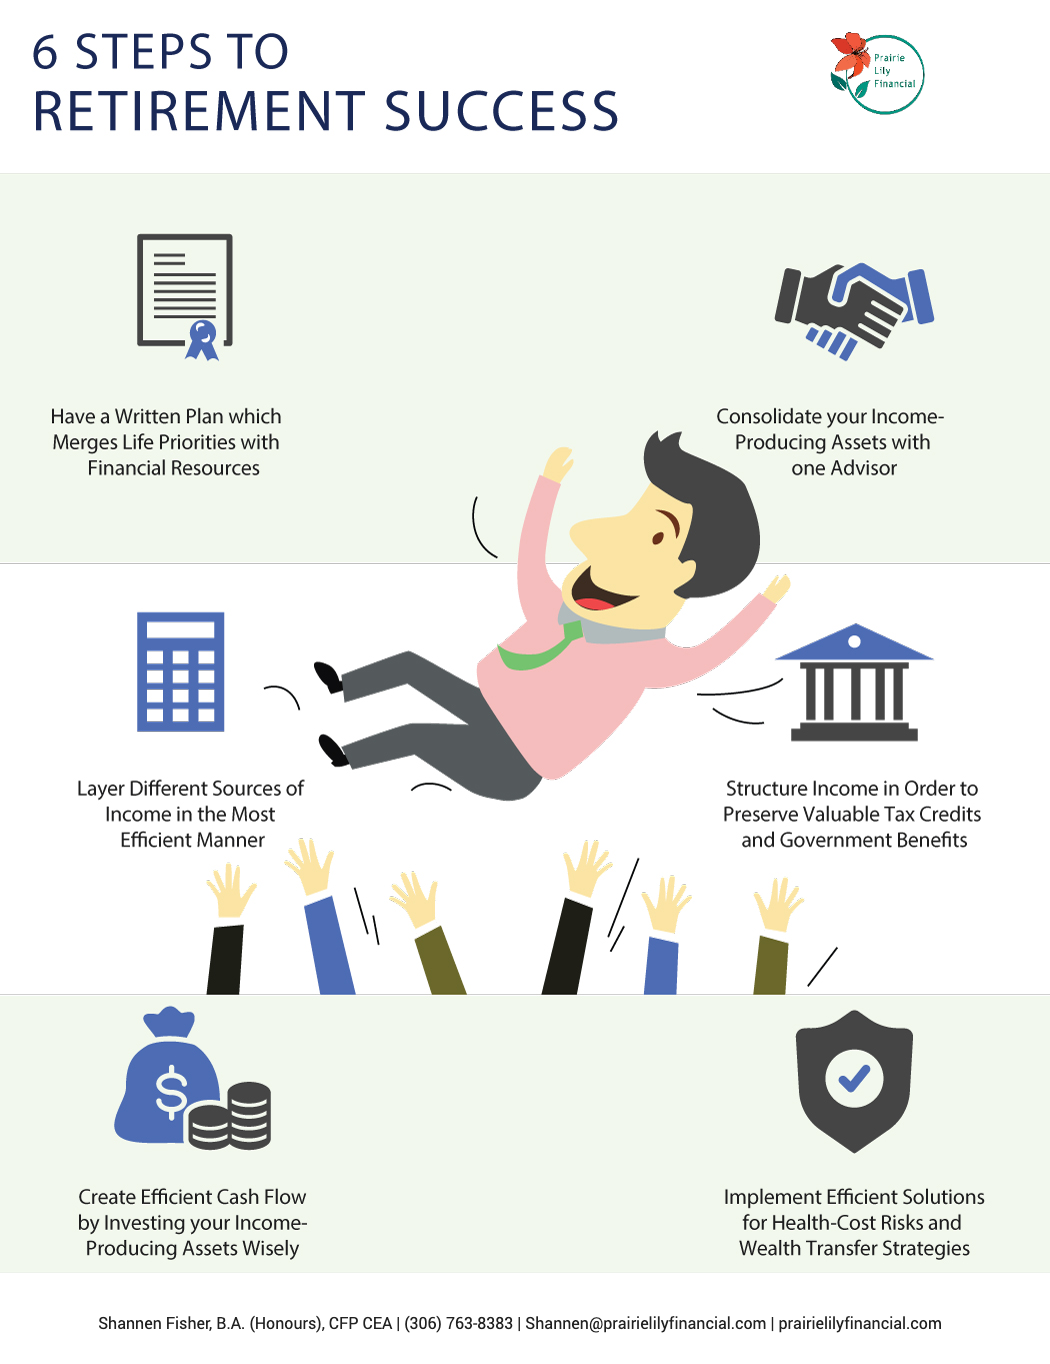
We’ve put together an infographic checklist that can help you get started on this. We know this can be a difficult conversation so we’re here to help and provide guidance to help you achieve your retirement dreams.

Income Needs

  • Determine how much income you will need in retirement.

  • Make sure you account for inflation in your calculations.

Debts

  • You should try to pay off your debts as soon as you can; preferably before you retire.

Insurance

  • As you age, your insurance needs change. Review your insurance needs, in particular your medical and dental insurance because a lot of plans do not provide health plans to retirees.

  • Review your life insurance coverage because you may not necessarily need as much life insurance as when you had dependents and a mortgage, but you may still need to review your estate and final expense needs.

  • Prepare for the unexpected such as a critical illness or a need for long-term care.

Government Benefits

  • Check what benefits are available for you upon retirement.

  • Canada Pension Plan- decide when would be the ideal time to apply and receive CPP payments. Business owners are in a unique position to control how much can be contributed to CPP by deciding to pay salary or dividends. (Dividends don’t trigger CPP contributions.)

  • Old Age Security- check pension amounts and see if there’s a possibility of clawback.

  • Guaranteed Income Supplement- if your income is low enough, you could apply for GIS.

Income

  • Are you a candidate for an individual pension plan (IPP)? IPPs can provide higher contributions than typically permitted to an RRSP and the ability to create a lifelong pension.

  • Check if your business is a candidate for a group RRSP or company pension plan. This is a great way for you to build retirement savings and provide benefits for your employees and business too.

  • Make sure you are saving on a regular basis towards retirement- in an RRSP, TFSA, or non-registered. Since you can control how you get paid, salary or dividends, dividends are not considered eligible income to create RRSP room, therefore you should make sure you have the optimal mix of both to achieve your financial goals.

  • Ensure your investment mix makes sense for your situation.

  • Don’t forget to check if there are any other income sources.  (ex. rental income, side hustle income, etc.)

Assets

  • The sale of your business can be part of your retirement nest egg. Therefore, you should make sure you know the valuation of your business and your plan to sell the business to your family, employees, partners or a third party. You should also know when you decide to sell your business too.

  • Are you planning to use the sale of your home or other assets to fund your retirement?

  • Will you be receiving an inheritance?

One other consideration that’s not included in the checklist is divorce. This can be an uncomfortable question, however divorce amongst adults ages 50 and over is on the rise and this can be financially devastating for both parties.

Next steps…

  • Contact Us about helping you get your retirement planning in order so your retirement dreams can be achieved.
https://prairielilyfinancial.com/wp-content/uploads/2022/10/retirementPlanningBO.jpeg 810 1440 Financial Tech Tools https://prairielilyfinancial.com/wp-content/uploads/2020/09/prairieLilyFinancail.png Financial Tech Tools2022-10-04 06:00:002022-10-04 14:41:26Retirement Planning for Business Owners – Checklist

Retirement Planning

September 1, 2021/in Blog, Family, health benefits, life insurance, Retirees, retirement, rrsp/by Financial Tech Tools

Most of us understand the benefits of sensible retirement planning. Still, it doesn’t feel relatively straightforward when it comes to creating your retirement strategy and putting it into effect. The reality is that, while there are lots of variables to consider, it isn’t as challenging to create an effective plan for retirement as you may think.

Firstly, let’s consider the merits of a retirement plan. Firstly, the plan will aid you in setting clear goals for your retirement, such as the age that you want to finish work and what you want your retirement to look like in terms of lifestyle. Secondly, it will help you establish how much you need to save to have a retirement that meets your objectives. Thirdly, a plan will allow you to choose your investment options wisely.

How you know how much you need to save is a common question. This depends on three factors:

  • Your age. It makes sense that starting to save for retirement when you are younger means that you need to save less money than starting later in life.

  • Benefits available to you. There is a range of federal government benefits that you might be eligible for, such as the Canada Pension Plan or Old Age Security.

  • Your plans for your retirement will inevitably affect how much you need to save to fund it.

If you haven’t started saving for your retirement yet or have less in your retirement savings plan than you would like, take a look at our top tips to accelerate your savings.

  • Make the most of RRSPs and TFSAs to minimize your tax bill and make your money grow faster.

  • Take advantage of any pensions or savings plans that your workplace offers, as your employer’s contributions can add extra value to your fund.

  • Look at your spending habits to identify opportunities to cut back outgoings and save more.

  • Think about putting spare money into your retirement fund.

Taking steps to create an effective retirement plan is a decision that will pay off as you approach later life, allowing you to have the savings for the retirement that you deserve.

Talk to us; we can help.

https://prairielilyfinancial.com/wp-content/uploads/2021/09/Retirement-planning.png 281 500 Financial Tech Tools https://prairielilyfinancial.com/wp-content/uploads/2020/09/prairieLilyFinancail.png Financial Tech Tools2021-09-01 06:00:002021-09-01 13:45:21Retirement Planning

Insurance Planning for Business Owners

July 1, 2021/in Blog, Business Owners, buy sell, corporate, disability insurance, Group Benefits, health benefits, Insurance, life insurance, travel insurance/by Financial Tech Tools

For business owners, making sure your business is financially protected can be overwhelming. Business owners face a unique set of challenges when it comes to managing risk. Insurance can play an important role when it comes to reducing the financial impact on your business in the case of uncontrollable events such as disability, critical illness or loss of a key shareholder or employee.

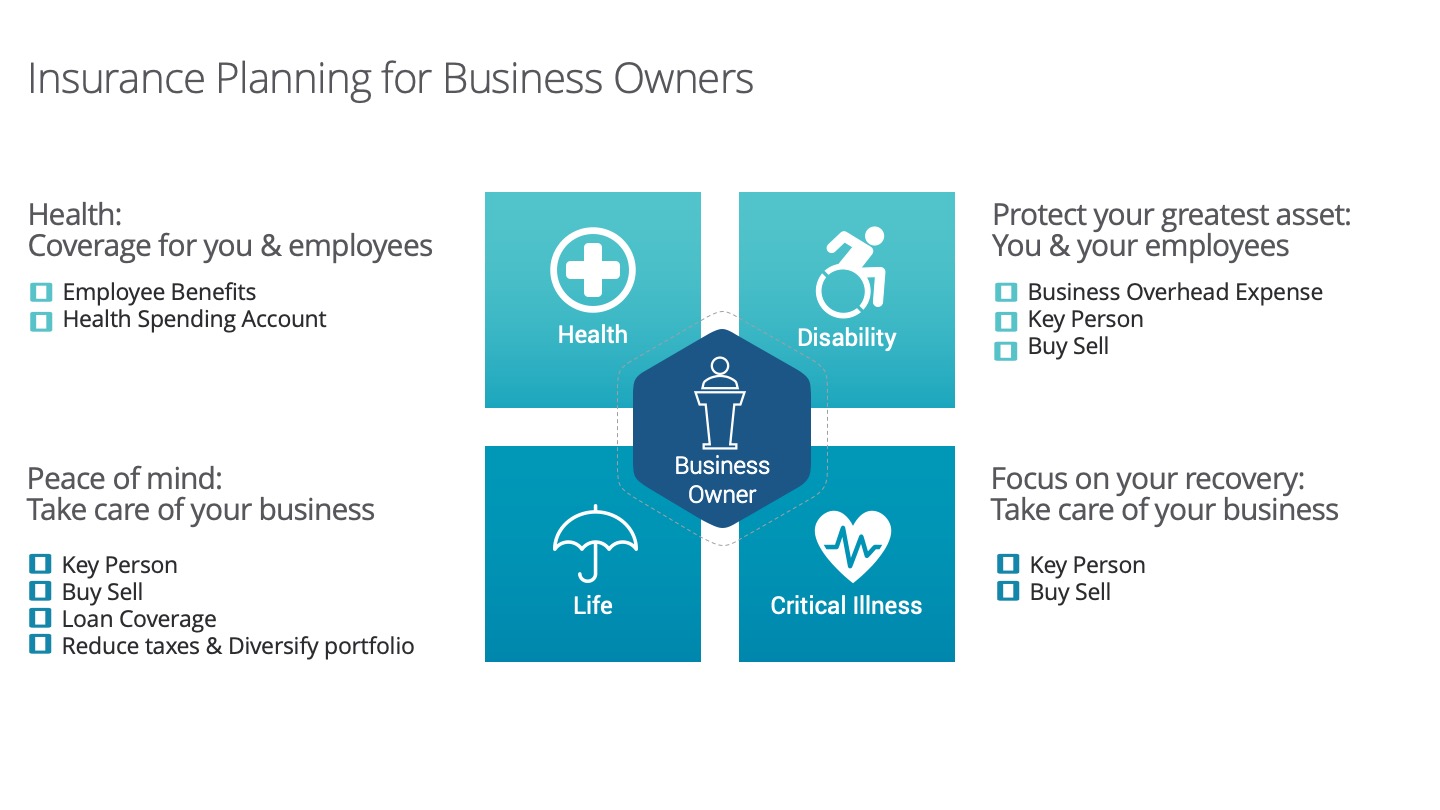
This infographic addresses the importance of corporate insurance.

The 4 areas of  insurance a business owner should take care of are:

  • Health

  • Disability

  • Critical Illness

  • Life

Health: We are fortunate in Canada, where the healthcare system pays for basic healthcare services for Canadian citizens and permanent residents. However, not everything healthcare related is covered, in reality, 30% of our health costs* are paid for out of pocket or through private insurance such as prescription medication, dental, prescription glasses, physiotherapy, etc.

For business owners, offering employee health benefits make smart business sense because health benefits can form part of a compensation package and can help retain key employees and attract new talent.

For business owners that are looking to provide alternative health plans in a cost effective manner, you may want to consider a health spending account.

Disability: Most people spend money on protecting their home and car, but many overlook protecting their greatest asset: their ability to earn income. Unfortunately one in three people on average will be disabled for 90 days or more at least once before the age of 65.

Consider the financial impact this would have on your business if you, a key employee or shareholder were to suffer from an injury or illness. Disability insurance can provide a monthly income to help keep your business running.

Business overhead expense insurance can provide monthly reimbursement of expenses during total disability such as rent for commercial space, utilities, employee salaries and benefits, equipment leasing costs, accounting fees, insurance premiums for property and liability, etc.

Key person disability insurance can be used to provide monthly funds for the key employee while they’re disabled and protect the business from lost revenue while your business finds and trains an appropriate replacement.

Buy sell disability insurance can provide you with a lump sum payment if your business partner were to become totally disabled. These funds can be used to purchase the shares of the disabled partner, fund a buy sell agreement and reassure creditors and suppliers.

Critical Illness: For a lot of us, the idea of experiencing a critical illness such as a heart attack, stroke or cancer can seem unlikely, but almost 3 in 4 (73%) working Canadians know someone who experience a serious illness. Sadly, this can have serious consequences on you, your family and business, with Critical Illness insurance, it provides a lump sum payment so you can focus on your recovery.

Key person critical illness insurance can be used to provide funds to the company so it can supplement income during time away, cover debt repayment, salary for key employees or fixed overhead expenses.

Buy sell critical illness insurance can provide you with a lump sum payment if your business partner or shareholder were to suffer from a critical illness. These funds can be used to purchase the shares of the partner, fund a buy sell agreement and reassure creditors and suppliers.

Life: For a business owner, not only do your employees depend on you for financial support but your loved ones do too. Life insurance is important because it can protect your business and also be another form of investment for excess company funds.

Key person life insurance can be used to provide a lump sum payment to the company on death of the insured so it can keep the business going until you an appropriate replacement is found. It can also be used to retain loyal employees by supplying a retirement fund inside the insurance policy.

Buy sell life insurance can provide you with a lump sum payment if your business partner or shareholder were to pass away. These funds can be used to purchase the shares of the deceased partner, fund a buy sell agreement and reassure creditors and suppliers.

Loan coverage life insurance can help cover off any outstanding business loans and debts.

Reduce taxes & diversify your portfolio, often life insurance is viewed only as protection, however with permanent life insurance, there is an option to deposit excess company funds not needed for operations to provide for tax-free growth (within government limits)  to diversify your portfolio and reduce taxes on passive investments.

Talk to us about helping making sure you and your business are protected.

Contact Us
https://prairielilyfinancial.com/wp-content/uploads/2021/07/insurancePlanningforBusinessOwnersFI.jpg 810 1440 Financial Tech Tools https://prairielilyfinancial.com/wp-content/uploads/2020/09/prairieLilyFinancail.png Financial Tech Tools2021-07-01 00:08:002021-07-01 00:18:14Insurance Planning for Business Owners

Personal Tax Planning Tips – End of 2020 Tax Year

December 2, 2020/in 2020 Only, Blog, Charitable Gifting, Coronavirus, Coronavirus - Associates, Coronavirus - Practice Owners, Coronavirus - Retired, Coronavirus - Retiring, Coronavirus - Students, disability, disability insurance, Family, financial advice, Financial Planning, health benefits, pension plan, rdsp, Registered Education Savings Plan, rrsp, tax, Tax Free Savings Account/by Financial Tech Tools

Now that we are reaching the end of the tax year, it’s an excellent time to review your finances. We’ve listed below some of the critical areas to consider and provide you with useful guidelines.

We have divided our tax planning tips into five sections:

  • Tax Deadlines

  • Individual tax issues

  • Family tax issues

  • Managing your investments

  • Retirement planning

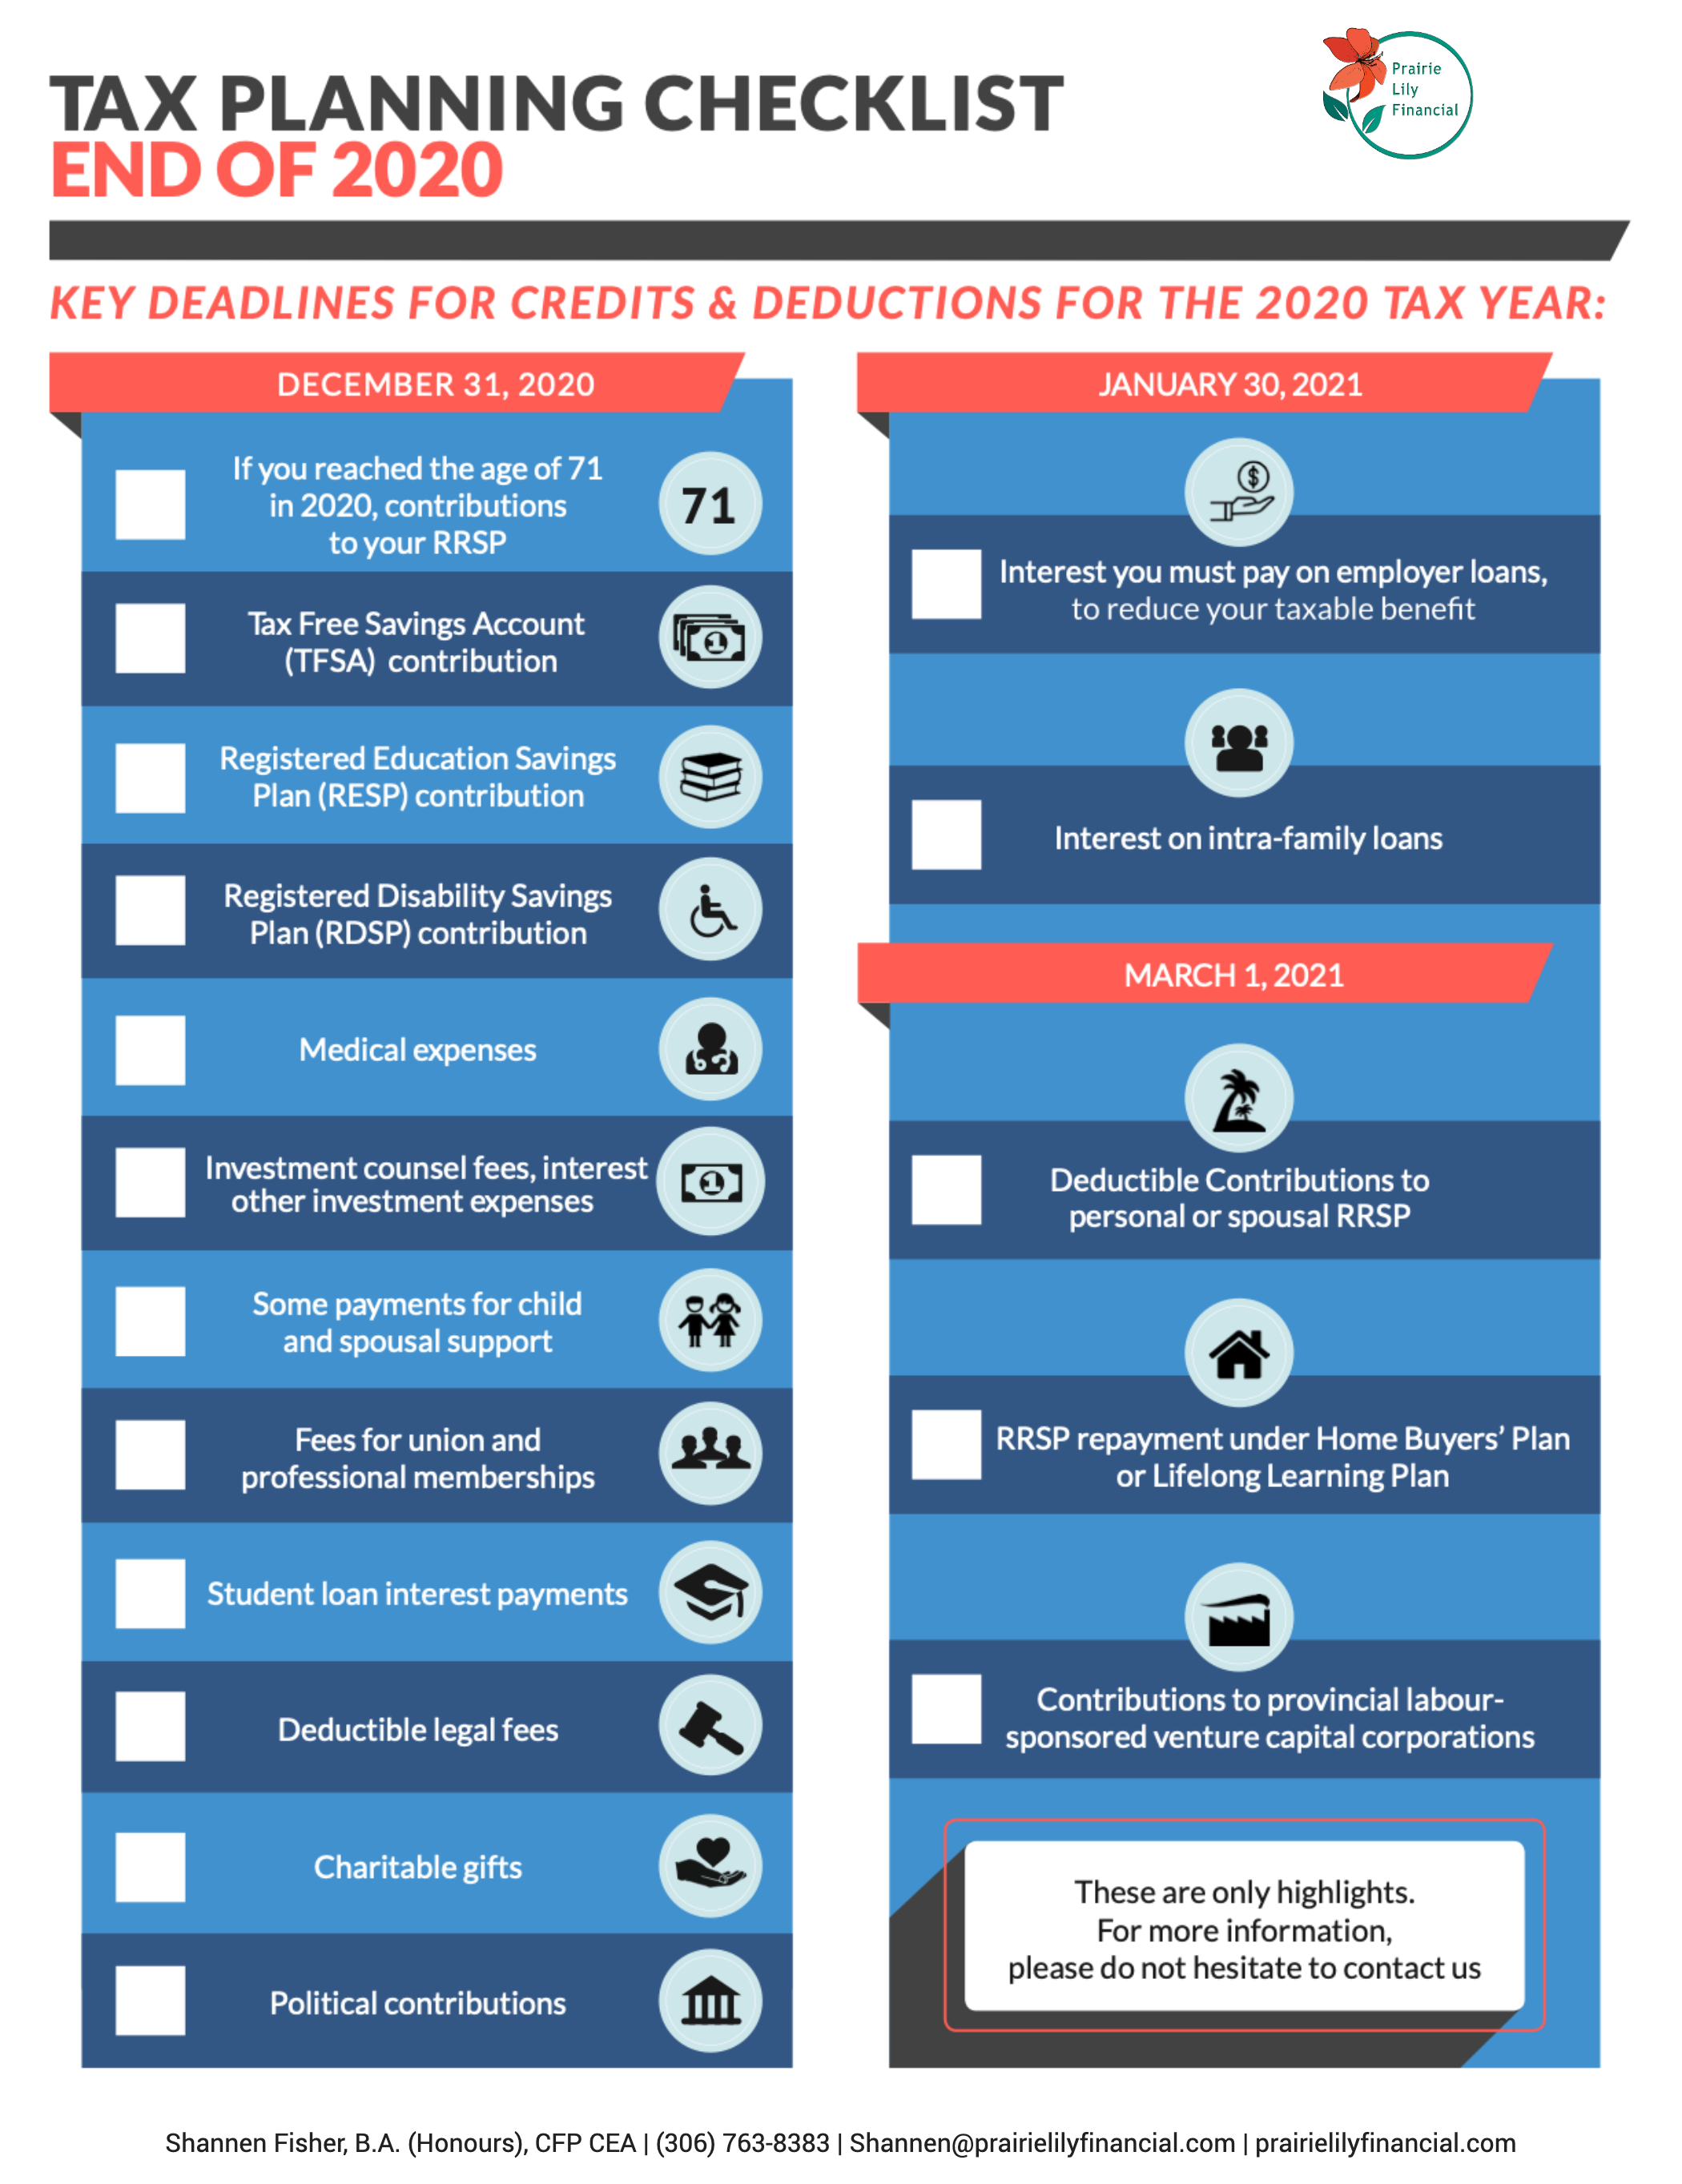
Tax Deadlines for 2020 Savings

December 31, 2020:

  • If you reached the age of 71 in 2020, you can’t contribute to your RRSP after this date

  • Use up your TFSA contribution room

  • Contribute to an RESP to get the Canadian Education Savings Grant (CESG) and the income-tested Canada Learning Bond (if eligible).

  • Contribute to an RDSP to get the Canada Disability Savings Grant (CDSG) and the income-tested Canada Disability Savings Bond (if eligible).

  • Medical expenses

  • Investment counsel fees, interest and other expenses relating to investments

  • Some payments for child and spousal support

  • Fees for union and professional memberships

  • Student loan interest payments

  • Deductible legal fees

  • Charitable gifts

  • Political contributions

January 30, 2021

  • Interest on intra-family loans

  • The interest you must pay on employer loans to reduce your taxable benefit

March 1, 2021

  • Contributions to provincial labour-sponsored venture capital corporations

  • RRSP Repayment under Home Buyers Plan or Lifelong Learning Plan

  • Deductible contributions to a personal or spousal RRSP

Individual Tax Issues

To help Canadians deal with financial hardships due to job loss because of COVID-19, the Canadian government introduced several benefit programs. If you received any of these benefits, you should be aware of the tax ramifications.

The Canada Emergency Response Benefit (CERB) was the first benefit program issued by the government and ran until September 26, 2020. If you received the CERB at all during 2020, the government will issue you at T4A, showing how much money you received from the CERB program. You must then declare that as income when filing your 2020 income tax return. Since no tax was taken off at the source, be sure to put aside money to pay for potential income taxes on your CERB income.

As of September 27, 2020, the government offered three replacement benefit programs:

  • Canada Recovery Benefit (CRB)
    This is for people impacted by COVID-19 who work but are not eligible for EI (e.g. self-employed).

  • Canada Recovery Sickness Benefit (CRSB)
    This is for people who are employed cannot work due to COVID-19 and do not have access to paid sick leave.

  • Canada Recovery Caregiving Benefit (CRCB)
    This is for people who must miss work to care for a family member who has COVID-19.

For all three of these programs, the government will be withholding 10% in taxes upfront, but you may end up owing extra tax, depending on the rest of your income for 2020, so it’s important to set extra money aside for taxes.

Also, there is a unique condition for the CRB only. If you make over $38,000 in 2020 (excluding the CRB), you will have to pay back the CRB at a rate of 50 cents for each dollar of CRB you earned above the threshold.

If you paid interest on an eligible student loan in 2020, you can claim a non-refundable tax credit in the amount of interest you paid by December 31. In addition, you should be aware that student loan payments were frozen for six months – from March 30 to September 30. No interest accrued on student loans during that period.

Family Tax Issues

  • Check your eligibility for the Canada Child Benefit
    (CCB)
    To receive the Canada Child Benefit in 2021/22, you need to file your tax returns for 2020 as the benefit is calculated using your family income from the previous year. Eligibility for the CCB depends on set criteria such as your family’s income, how many children you have, and how old they are. You may qualify for a full or partial amount, depending on whether you have full custody or shared custody.

  • Consider family income splitting

    The CRA offers a prescribed low-interest rate on family loans. Therefore, it makes sense to consider setting up an income splitting loan arrangement with your family members. If you do this, you can potentially lock in a family loan at a low-interest rate of 1% and then invest the borrowed money into a higher return investment while benefitting from your family member’s lower tax status. Don’t forget to adhere to the Tax on Split Income rules.

Managing Your Investments

  • Use up your TFSA contribution room

    If you can, it’s worth contributing the full $6,000 to your TFSA for 2020. You can also contribute more (up to $69,500) if you are 29 or older and haven’t made any previous TFSA contributions.

  • Contribute to a Registered Education Savings Plan (RESP)

    The Registered Education Savings Plan (RESP) is a savings plan for parents and others to save for a child’s education. The Canada Education Savings Grant (CESG) will match up to 20% of your contributions up to a maximum of $2,500.

    That means the CESG can add a maximum of $500 to an RESP each year. The grant room accumulates until your child turns 17. Therefore, any unused CESG amounts for the current year are automatically carried forward for possible use in the future years.

    The income-tested Canada Learning Bond (CLB) is paid directly to a child’s RESP by the Canadian government to low-income families. No personal contributions are required to receive the CLB.

  • Contribute to a Registered Disability Savings Plan (RDSP)

    The Registered Disability Savings Plan (RDSP) is a savings plan for parents and others to save for the financial security of a person who is eligible for the Disability Tax Credit (DTC). The government will pay a matching Canada Disability Savings Grant (CDSG) up to 300% – depending on the beneficiary’s adjusted family net income and amount contributed.

    Also, low-income Canadians with disabilities may be eligible for a Canada Disability Savings Bond (CDSB). If you qualify, it will be paid directly to your RDSP.

    The government will pay matching grants or bonds into the RSDP up to and including the end of the year the recipient turns 49. Be aware that there is a 10-year carry-forward of CDSG and CDSB entitlements.

  • Donate securities to charity

    Donating by year-end will provide you with tax savings. If you donate eligible securities or mutual funds, capital gains tax does not apply, and you can receive a tax receipt for their full market value. Also, the charity gets the full value of the securities.

  • Think about selling any investments with unrealized capital losses

    It might be worth doing this before year-end to apply the loss against any net capital gains achieved during the last three years. The last trading date for 2020 for Canadian and US publicly traded stocks will be Tuesday December 29th in order to record the gain or loss in the 2020 taxation year.

    Conversely, if you have investments with unrealized capital gains that cannot be offset with capital losses, it may be worth selling them after 2020 to be taxed on the income the following year.

  • Consider the timing of purchasing of certain non-registered investments

    Suppose you are considering purchasing an interest-bearing investment like a guaranteed investment certificate (GIC) with a maturity date of one year or more. In that case, you may consider delaying the purchase to the following year, so you don’t have to pay tax on accrued interest until 2021. You should also consider this with mutual funds that make taxable distributions before the end of 2020, consider delaying this until early 2021. Don’t pay taxes earlier than necessary.

  • Check if you have investments in a corporation

    The new passive investment income rules apply to tax years from 2018 onwards. They state that the small business deduction is reduced for companies with between $50,000 and $150,000 of investment income. Therefore, the small business deduction has entirely stopped for corporations that earn a passive investment income of more than $150,000.

    Note – At a provincial level, both Ontario and New Brunswick do not follow the federal rules to limit access to the small business deduction.

Retirement Planning

  • Make the most of your RRSP

    The deadline for making contributions to your RRSP for the year 2020 is March 1, 2021. The deduction limit for 2020 is limited to 18% of the income you earned in 2020, to a maximum of $27,230. This maximum amount is impacted by the following:

  1. Any pension adjustment

  2. Any previous unused RRSP contribution room

  3. Any pension adjustment reversal.

Remember that deducting your RRSP contribution reduces your after-tax cost of making said contribution.

  • Check when your RRSP is due to end

    If you reach the age of 71 during 2020, you must wind up your RRSP this year. You must make your final contribution to it by December 31, 2020.

  • Convert to RRIF before year-end

    If you turned 65 during 2020 or are already older than 65, you’re entitled to a pension credit that can fully or partly offset the tax on the first $2,000 of eligible income annually. Consider setting up an RRIF before year-end to pay out $2,000 annually if you don’t have any other eligible pension income.

If you have any questions about your taxes for 2020, contact us – we can help you!

https://prairielilyfinancial.com/wp-content/uploads/2020/12/[email protected] 563 1000 Financial Tech Tools https://prairielilyfinancial.com/wp-content/uploads/2020/09/prairieLilyFinancail.png Financial Tech Tools2020-12-02 14:07:542020-12-02 15:03:56Personal Tax Planning Tips – End of 2020 Tax Year

Book a Meeting

Get in Touch

, 

T: 
E:

,

  • Why A Buy-Sell Agreement Is Vital For Your Business
  • Tax Tips You Need To Know Before Filing Your 2022 Taxes
  • When and Why You Should Conduct an Insurance Audit
  • Federal Budget 2023 Highlights
  • Saskatchewan 2023 Budget Highlights

About

Cultivating financial security and independence for you and your loved ones. Our goal for our clients is to grow financial prosperity for anyone who wants it through financial education.

pride
©2020 Financial Tech Tools Inc. | Privacy Statement and Terms of Use
  • Link to LinkedIn
  • Link to X
Scroll to top Scroll to top Scroll to top